If you’ve been watching mortgage rates lately, you might feel a little stuck. Rates climbed above 7% this year, and a lot of buyers have decided to sit tight and wait for them to come back down.
But rates are only half the story. When you buy a home, you usually get one of two things: low rates or negotiating power. It’s rare to get both at the same time. And right now, you have a lot more of that second one than you might think.
Why Low Rates and Leverage Don’t Usually Show Up Together
Think back to 2020 and 2021. Rates were near 3%, and buyers rushed into the housing market. Those low rates sounded great, but they came with a catch. There were a lot of buyers just like you that you had to compete with – and there weren’t enough homes for sale to meet that demand.
That’s why homes got multiple offers, buyers paid over asking or waived inspections, and sellers held all the cards. Jake Krimmel, Senior Economist at Realtor.com, shows just how one-sided things got:
“Seller’s markets peaked at 98 of 100 metros in spring 2022 after two years of mortgage rates near 3%.”
Then, in the second half of 2022, rates went up. As a result, the number of people buying homes went down, inventory grew, and the balance slowly started tipping from sellers back to buyers. Fast forward to today, and that flip is officially here.
In a recent report, Realtor.com found about two-thirds (66) of the top 100 metros now lean in favor of buyers (see graph below):
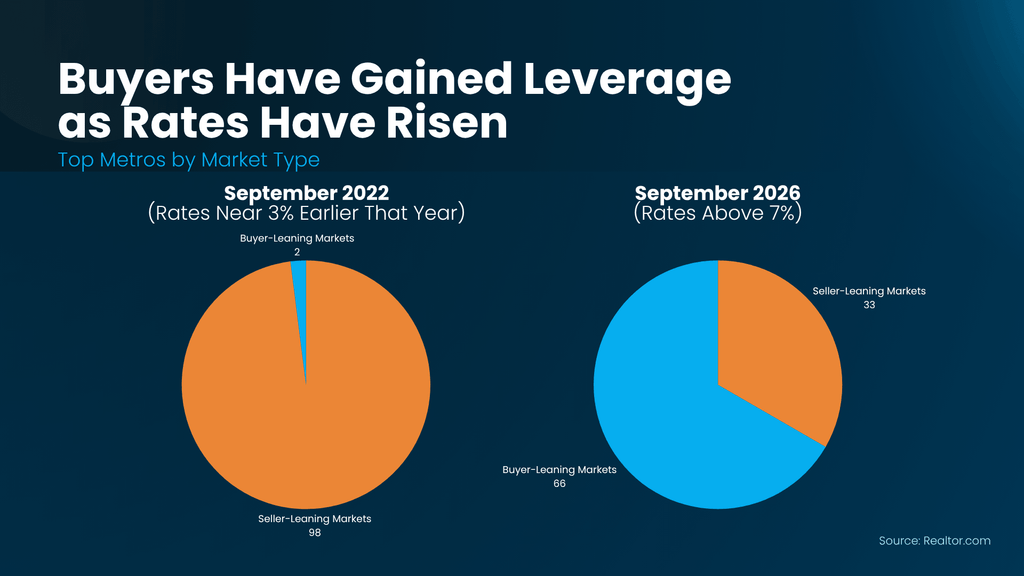
And while you may want lower rates, this shift in power has its own perks.
What Your Leverage Looks Like Right Now
There are more homes for sale than there have been in years. And in a more buyer-friendly market like that, it means sellers have to work harder to get their homes sold. As Lawrence Yun, Chief Economist at the National Association of Realtors (NAR), says:
“Higher inventory and lengthening days on market give buyers improved negotiating power.”
That shows up in the deals buyers are getting. According to Redfin, nearly half of buyers now get some kind of concession from the seller – like help with closing costs, money for repairs, or even the seller paying to buy down your mortgage rate (see graph below):
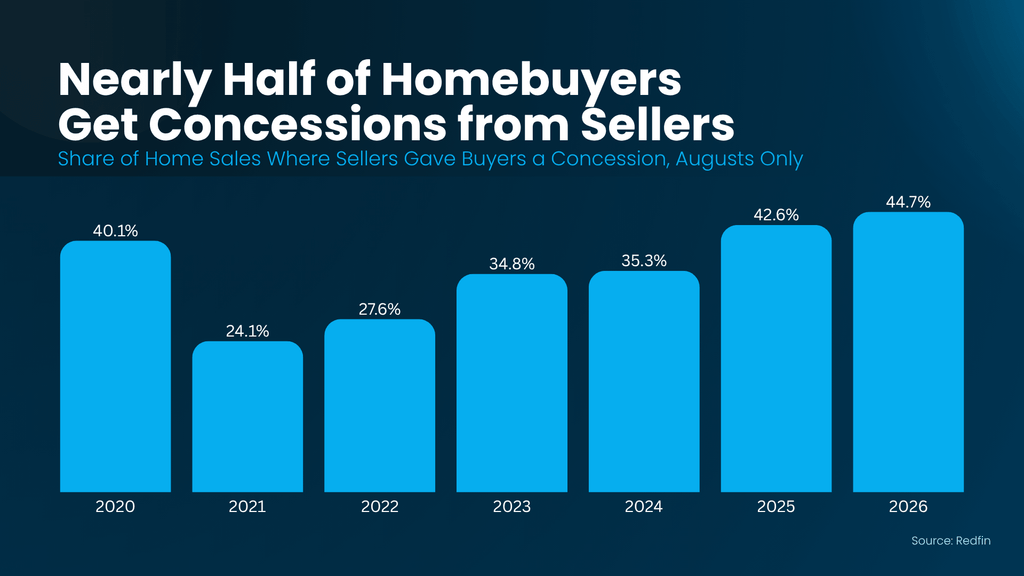
So when you find a home you love, even if the rate isn’t what you necessarily wanted, there are other levers to pull. Ask about a price cut or a seller-paid rate buydown, too. It could take some of the sting out of today’s rates.
Why Waiting for Lower Rates Could Backfire
And just in case you’re still thinking you’ll just hold off until rates drop, here’s what you should know. Experts at Fannie Mae, the Mortgage Bankers Association (MBA), and Wells Fargo don’t expect rates to fall much through 2027 (see graph below):
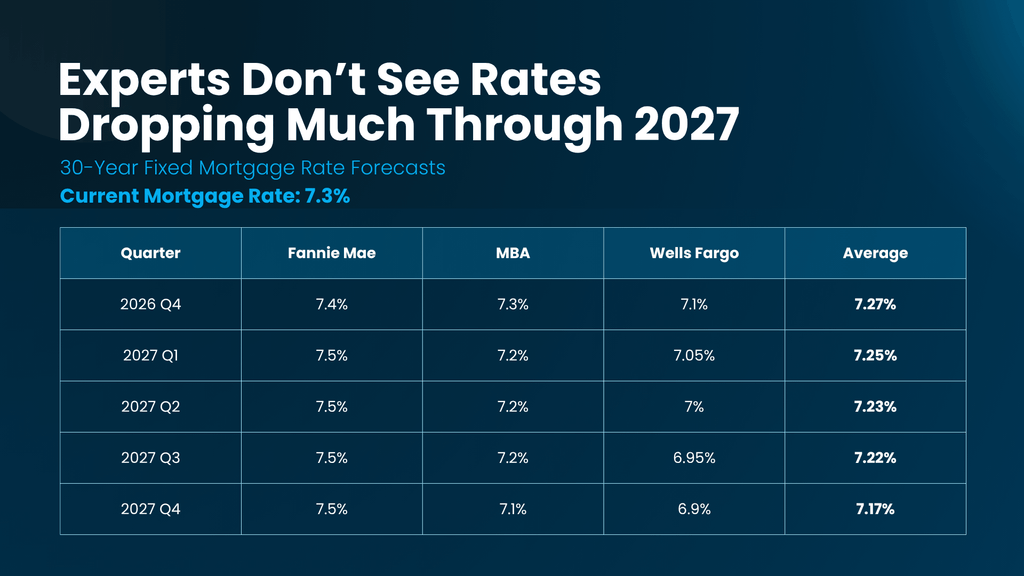
And here’s the whole point. Even if rates did drop in a big way, a lot of buyers would rush back in. More competition means fewer deals, fewer concessions, and sellers getting the upper hand again.
So waiting comes with a trade-off. You might land a better rate down the road, but you’d probably give up the bargaining power you have today.
That doesn’t mean you have to move right now. You should only buy when the numbers work for you. But if you’ve got a real reason to move, today’s leverage could help make your numbers work – even at today’s rates.
Bottom Line
Buyers rarely get low rates and strong negotiating power at the same time, and today’s market is handing you the leverage.
Let’s find homes where sellers may be open to covering a rate buydown or closing costs, so you can see if today’s market can work for your budget.
Join The Discussion