Half the buyers out there are scared home prices are about to crash. The other half are hoping they will.
A recent survey from Clever found 58% of Gen Z buyers are actually rooting for a crash, just so homeownership feels within reach.
So, what do the forecasts actually say?
Every quarter, Fannie Mae surveys more than 100 housing experts on where prices are headed. The newest results are in. And spoiler alert: they’re not calling for a crash – not even the pessimists.
What the Newest Numbers Actually Say
The panel’s latest forecast has prices climbing every single year through at least 2030.
The panel’s average forecast is that prices will rise by 14.7% in the next 5 years. And here’s where it gets really interesting. If you split these experts into optimists and pessimists, even the pessimists still expect prices to increase about 6.6% by the end of 2030 (see graph below):
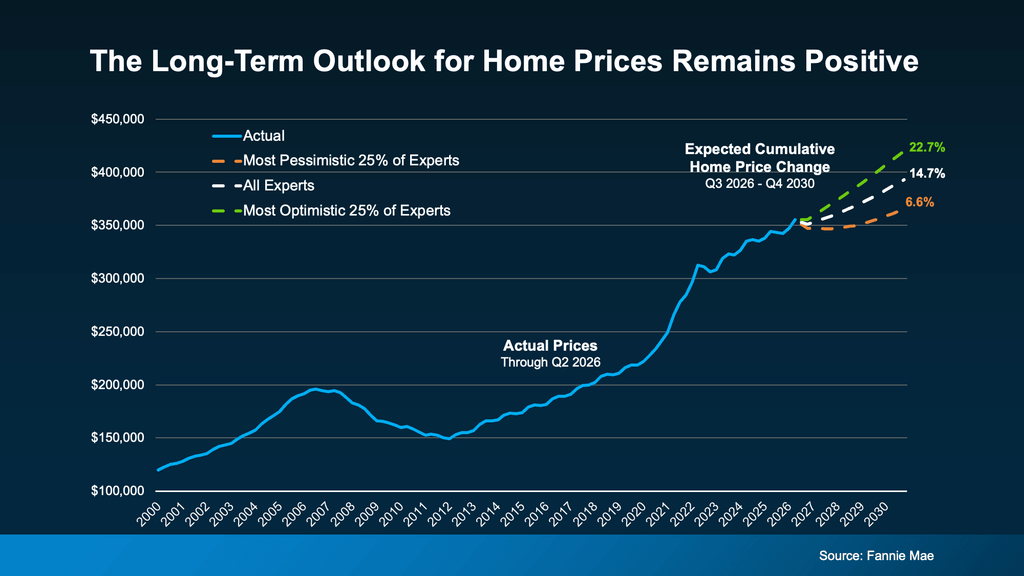
The takeaway? If you’ve been waiting for prices to fall, you may be waiting a while.
One thing to keep in mind though – these are national numbers. Prices in your area could run a little hotter or a little cooler than this, so it helps to know what’s happening locally, too. But the big picture is prices aren’t crashing. Historically prices usually rise.
How This Quarter Compares to the Past
Here’s something you probably don’t realize. This survey runs 4 times every year, so you can track the panel’s mood over time.
A year ago, the panel expected home prices to grow 2.1% this year. Now they’re forecasting 2.5%. That means the near-term outlook actually got more optimistic. But that’s only part of the story. The years after that shifted, too (see graph below):
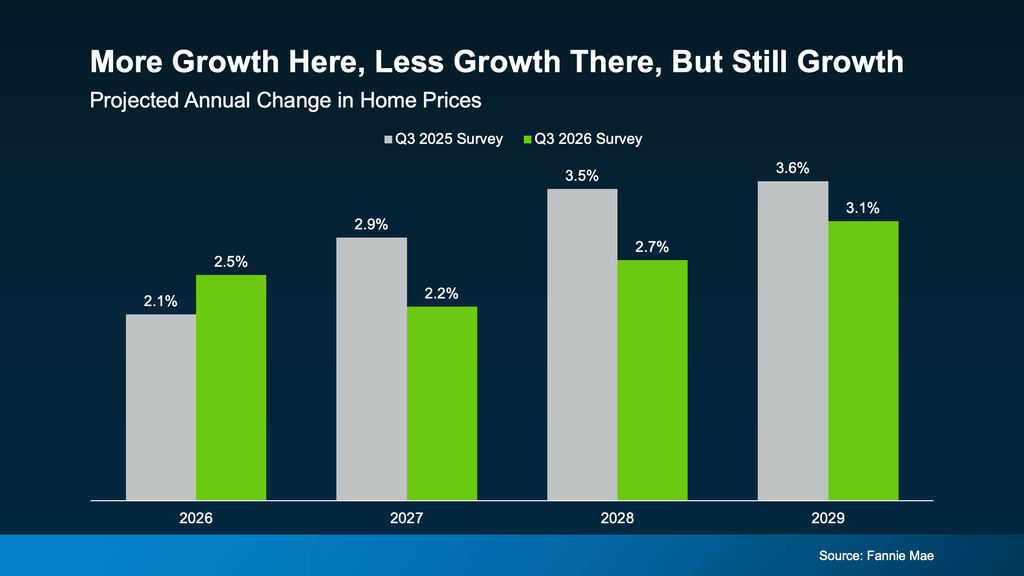
Zoom out to 2027 through 2029 and the mood has cooled a bit. Each of those years is now expected to see a little less growth than the panel thought a year ago. That’s likely a reflection of where we are right now with everything that’s impacting the housing market.
But again, the overall takeaway here is every bar shows an increase in prices – the size of that increase has just moderated due to some of the factors at play.
A slower climb isn’t a bad thing, though. It’s a sign the market is settling into a more normal pace after a few wild years.
A little more growth here, a little less growth there. What hasn’t budged once is the idea that home prices will keep growing.
What It Means for Your Next Move
Now, percentages are great, but you probably care more about the actual dollars and cents of your move, so let’s graph that out, too.
Run the numbers on a $400,000 home bought in January, and the panel’s latest forecast puts you up about $58,000 in equity in 5 years just from price growth (see graph below):
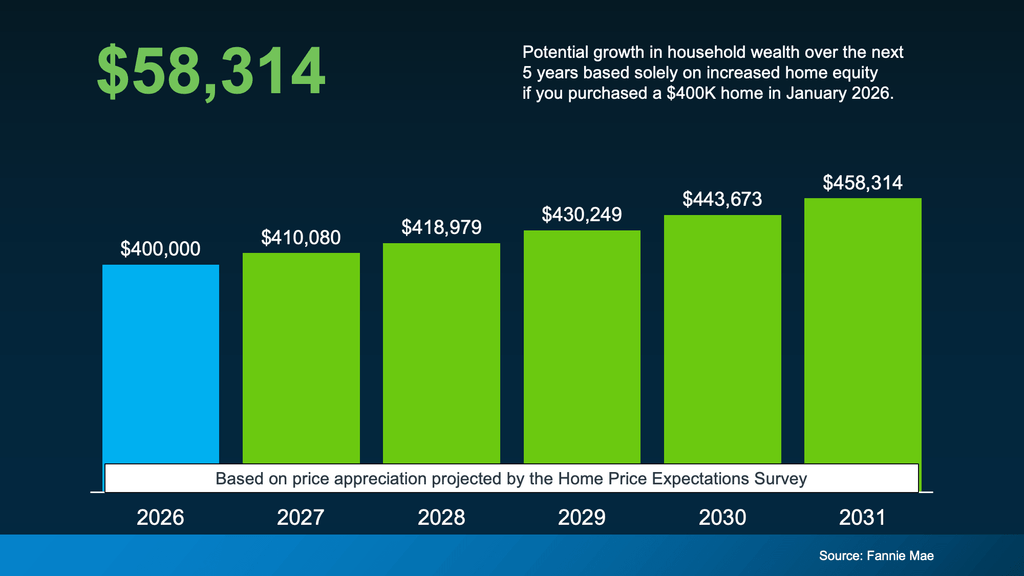
That’s real wealth you could be building while others sit on the sidelines, waiting for a crash the experts don’t see coming. And with prices expected to keep rising, waiting could mean paying more for the same home later.
Bottom Line
Whether you’re bracing for a crash or hoping for one, the verdict is the same – prices are still expected to rise, not fall. Let’s talk about what that means for your market and your plans.
Join The Discussion